India Battery Energy Storage System (BESS) Market and Forecast to 2032 - Analysis by Application (Utility, Commercial and Industrial, Residential), Battery Type, Storage System, Connection Type, Energy Capacity, and Geography
India Battery Energy Storage System (BESS) Market Size
The India Battery Energy Storage System market has recorded significant growth in recent years, driven by accelerating renewable energy deployment, rising power demand, rapid battery cost declines, and growing government support for energy storage infrastructure. Expanding solar and wind capacity additions have increased the operational requirement for battery storage systems to ensure grid stability, peak load management, and reliable power supply across the country.
The growing imperative to achieve India's renewable energy targets and modernise the power grid has accelerated investments in utility-scale and standalone BESS projects. Increasing adoption of battery storage by commercial and industrial consumers is simultaneously supporting market expansion across multiple end-use segments, reinforcing the breadth of demand within the India battery energy storage market.
The market continues to benefit from a supportive policy environment, including viability gap funding, the ACC PLI scheme, and increasing investments in battery manufacturing and gigafactory developments. Technological advancements in lithium-ion batteries and the progressive expansion of domestic energy storage manufacturing capabilities are further consolidating the long-term growth prospects of the India BESS market.
Key Drivers Shaping the India BESS Market
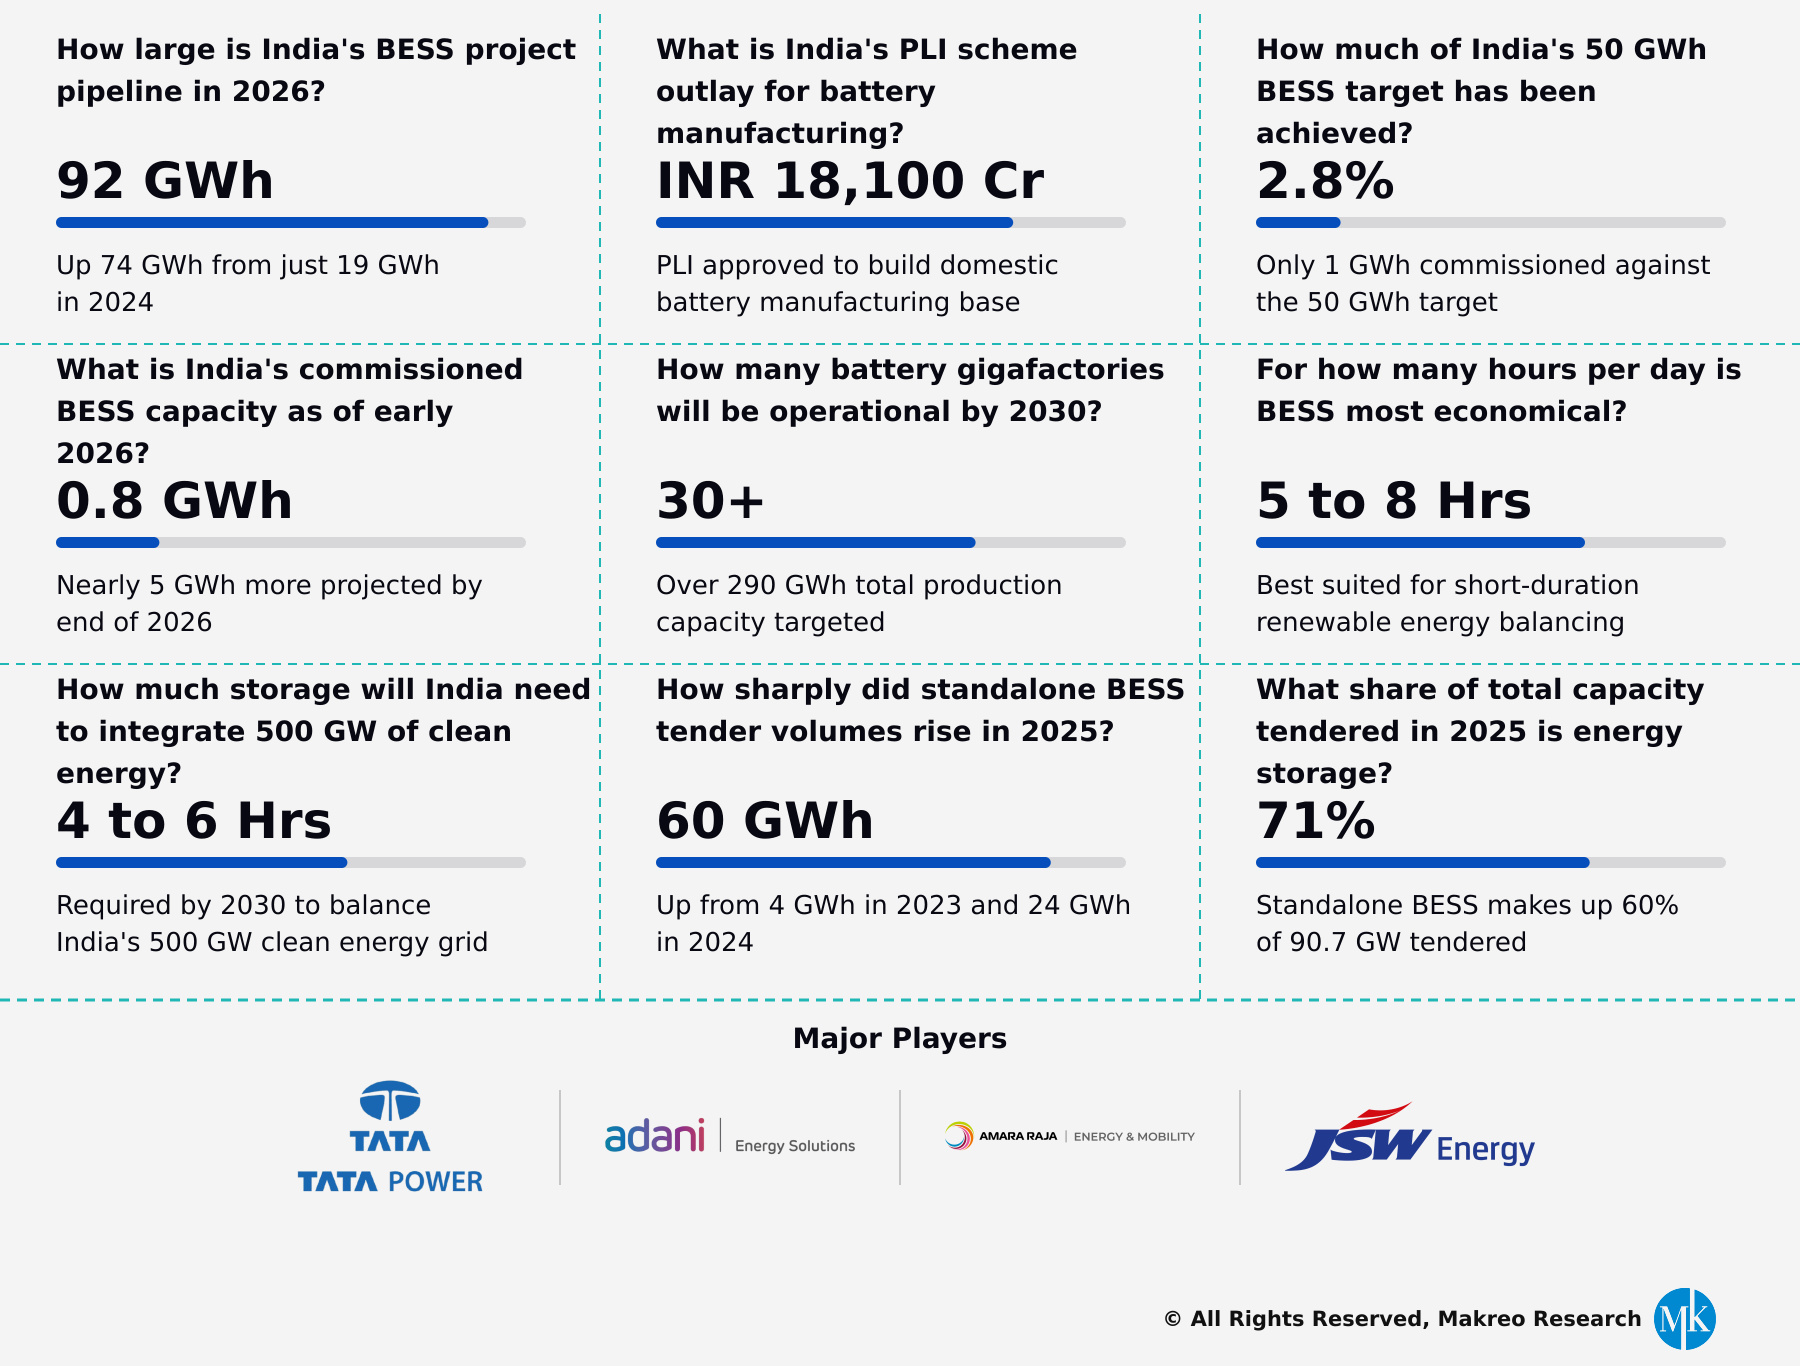
Several policy, technological, and market-driven factors are accelerating growth across the India BESS market, spanning renewable energy integration, battery manufacturing expansion, and increasing grid-scale deployments.
-
Rapid Growth in Renewable Energy Capacity Increasing Storage Demand - India's ambitious renewable energy targets and rising solar and wind installations are increasing demand for battery energy storage systems to manage generation intermittency, ensure grid stability, and support reliable power supply across the country.
-
Government Support and Policy Initiatives Encouraging BESS Adoption - Supportive measures including Viability Gap Funding, ISTS waiver benefits, the ACC PLI scheme, and state-level energy storage policies are encouraging investment in battery storage projects and domestic manufacturing across the India BESS market.
-
Declining Battery Costs Supporting Utility-Scale Deployments - Falling lithium-ion battery prices, technological advancements, and economies of scale are improving the economics of battery storage systems, accelerating adoption across utility-scale and commercial and industrial applications in India.
-
Expansion of Grid-Scale Tenders and Energy Storage Pipeline - Increasing standalone BESS tenders and large-scale storage procurements by SECI, NTPC, and state utilities are driving deployment activity and strengthening the India BESS project pipeline across key states.
-
Growing Investments in Battery Manufacturing and Gigafactories - Rising investment in lithium-ion battery production facilities and gigafactory projects is supporting manufacturing localisation, reducing import dependence, and strengthening India's domestic energy storage ecosystem.
India BESS Industry Insights
India BESS Market Revenue, 2023 - 2032F
Makreo Research
Renewable Integration and Grid Storage Investment
The India Battery Energy Storage System market has recorded rapid and sustained growth in recent years, driven by accelerating renewable energy deployment, increasing grid modernisation investments, and rising demand for reliable and flexible power infrastructure across utility-scale, commercial, and industrial applications. This growth momentum is reflected in a CAGR of 29.05% during 2026-2032, underscoring the market's robust near-term expansion trajectory.
Looking ahead, ongoing gigafactory expansion, continued advancements in battery technologies, and increasing investments in long-duration energy storage solutions are expected to further strengthen the long-term outlook of the India BESS market through the forecast period.
India BESS Market Segmentation by Application, by Value, 2026E
Utility-Scale Segment - Leading Application by Market Value
The utility-scale segment is estimated to account for the largest share of the India Battery Energy Storage System market by value in 2026. India awarded 10.4 GW of standalone BESS capacity during 2025, with the majority of projects concentrated in the utility-scale segment under SECI, NTPC, and state utility tenders, accelerating the dominance of utility-scale storage deployments across the country.
The utility-scale BESS pipeline in India exceeded 90 GWh by 2025, supported by government-backed Viability Gap Funding schemes and India's expanding renewable energy capacity targets.
India Installed BESS Capacity, 2023 – 2032F
Makreo Research
Strategic Investments and Developments in the India BESS Market
Tata Power Renewable Energy - Renewable Capacity and Green Energy Expansion
On March 7, 2026, Tata Power Renewable Energy Limited announced plans to invest approximately INR 49,000 crore, equivalent to around USD 5.6 billion, to develop 7 GW of solar, wind, hybrid, and storage-based renewable projects in Andhra Pradesh. The investment significantly strengthens Tata Power's clean energy and battery storage portfolio, reinforcing its position as a leading developer within the India renewable energy storage market.
Amara Raja Energy and Mobility - 1 GWh Lithium Storage Deployment Milestone
On April 22, 2026, Amara Raja Energy and Mobility Limited announced that it had surpassed 1 GWh of cumulative lithium-based energy storage deployment across India's telecom sector, with installations at more than 50,000 telecom sites nationwide. The milestone reinforces Amara Raja's leadership in the India lithium-ion battery storage market and its expanding operational footprint across critical infrastructure applications.
JSW Energy - BESS Pipeline Expanded to 29.6 GWh
In November 2025, JSW Energy disclosed that its locked-in energy storage pipeline had expanded to approximately 29.6 GWh, positioning it among the largest private-sector BESS pipelines in India. The portfolio includes standalone BESS, pumped hydro storage, and hybrid renewable-storage projects, reflecting JSW Energy's diversified approach to India BESS project development across multiple storage technologies and application segments.
Adani Group - India's Largest BESS Project at Khavda, Gujarat
On November 12, 2025, the Adani Group announced a 1,126 MW / 3,530 MWh BESS project at Khavda, Gujarat, marking India’s largest battery energy storage project and strengthening the group’s presence in the BESS market.
Recent Funding Activity in the India BESS Market
-
March 2026 - Exide Energy Solutions Ltd. secured INR 450 crore in strategic funding from Exide Industries to support EV battery and stationary energy storage manufacturing expansion in India.
-
February 2026 - Exide Energy Solutions Ltd. raised an additional INR 100 crore through a rights issue to support the setup of its Bengaluru lithium-ion plant, taking cumulative investments in the company beyond INR 4,352 crore.
-
August 2025 - Amara Raja Energy and Mobility Ltd. invested INR 1,200 crore toward developing a lithium-ion gigafactory, energy storage system solutions, and an advanced cell manufacturing ecosystem.
Scope of the Study for India BESS Market
Makreo Research has published a comprehensive report titled "India Battery Energy Storage System (BESS) Market and Forecast to 2032 - Analysis by Application (Utility, Commercial and Industrial, Residential), Battery Type, Storage System, Connection Type, Energy Capacity, and Geography". The study delivers an in-depth assessment of the India BESS industry, covering market evolution, technology advancements, supply chain developments, and future growth prospects through 2032.
The report opens by evaluating the overall development of the India BESS market, with particular focus on the structural elements and demand-side forces shaping industry trajectory, including:
Revenue and Demand Analysis
-
The study provides a comprehensive analysis of the India BESS market, covering historical market performance, current industry developments, and battery storage deployment trends across the country.
-
The report evaluates installed and projected BESS capacity across India, alongside battery manufacturing capacity and state-wise deployment trends, providing a granular view of regional growth dynamics.
-
A comparative assessment of key battery storage technologies is provided, covering lithium-ion batteries and other emerging storage technologies across major performance parameters.
-
The report also analyses key government policies, incentives, and regulatory initiatives supporting battery storage adoption, including VGF support, ACC PLI schemes, ISTS waiver benefits, and state-level energy storage policies.
-
Detailed segmentation analysis is presented across application, connection type, battery type, energy capacity, ownership model, storage system, components, and regions, highlighting key demand patterns, investment opportunities, and deployment trends across major end-use sectors and geographies.
India Battery Manufacturing and Supply Chain Dynamics
-
A dedicated section evaluates India's battery ecosystem, covering battery cell manufacturing, module assembly, energy storage systems, and localisation initiatives aimed at strengthening the domestic value chain across the India battery storage industry.
-
The report analyses India's efforts to reduce import dependency through the ACC PLI scheme, gigafactory developments, and investments by leading battery manufacturers and energy companies, assessing the structural progress being made toward domestic manufacturing self-sufficiency within the India battery cell manufacturing market.
-
The study further assesses battery manufacturing expansion plans, critical raw material requirements, and supply chain challenges impacting the growth trajectory of the India BESS market, providing stakeholders with a structured view of the risks and opportunities shaping India's energy storage supply chain outlook.
India BESS Tender and Tariff Landscape
-
The report provides a comprehensive assessment of India's utility-scale BESS tendering ecosystem, covering standalone storage tenders, deployment pipelines, and procurement activities undertaken by central and state agencies including SECI, NTPC, and state utilities across key markets such as Rajasthan, Gujarat, Maharashtra, and Tamil Nadu.
-
The analysis evaluates auction tariff trends, state-wise price discovery, tender growth, and the expansion of the India BESS project pipeline, alongside the impact of localisation initiatives, duty reforms, and policy support mechanisms on project economics and deployment activity across the India BESS market.
India BESS Pricing and Cost Structure Analysis
The study presents a detailed analysis of India BESS pricing benchmarks, standalone system costs, and component-wise cost structures, providing a granular view of project economics across the India battery energy storage system market. Battery technology economics, maintenance costs, and component-level contributions to overall project costs are evaluated, identifying the factors influencing BESS project viability across utility-scale and commercial and industrial applications.
The study further examines the impact of declining battery prices, technology advancements, and manufacturing scale expansion on the long-term competitiveness of the India BESS market.
Competitive Landscape and Key Market Participants
-
A comprehensive competitive benchmarking section compares leading BESS developers, battery manufacturers, system integrators, and technology providers based on market share, infrastructure capacity, technology adoption, product portfolio, and strategic expansion initiatives within the India BESS competitive landscape.
-
Detailed company profiles provide insights into business operations, financial performance, manufacturing capabilities, project portfolios, product offerings, and market positioning across the India battery energy storage system market.
-
The report further analyses grid-scale BESS capacities awarded, gigafactory expansion plans, strategic partnerships, investments, mergers and acquisitions, funding activities, and other competitive developments shaping the India BESS market through the forecast period.
Market Challenges and Emerging Opportunities
-
The study identifies the principal challenges constraining growth across the India BESS market, including dependence on imported battery cells and critical minerals, high upfront project costs, supply chain constraints, evolving regulatory frameworks, and current limitations in domestic manufacturing capabilities within the India battery storage industry.
-
The report simultaneously highlights significant structural growth opportunities shaping the India BESS market outlook through 2032, including rising renewable energy integration requirements, increasing demand for grid stability solutions, expansion of utility-scale storage projects, growing electricity demand, and supportive government initiatives including VGF schemes, ACC PLI incentives, and state-level energy storage policies.
Future Outlook and Forecast Analysis
-
The report concludes with detailed forecasts for the India BESS market through 2031, including market size estimates, installed battery storage capacity projections, and state-wise deployment outlook.
-
Forecasts are supported by scenario analysis, renewable energy targets, investment outlook, tender pipeline growth, and technology adoption trends.
-
The study further evaluates the long-term strategic direction of the India BESS market, driven by increasing renewable energy demand, grid modernization initiatives, and the expansion of domestic battery manufacturing capabilities.
-
2023 - 2026: Past and Present Scenario
-
2026: Base year of study
-
2026 - 2032: Future Outlook
India BESS Market Segmentation
-
Front-of-the-meter
-
Behind-the-meter
-
Lithium-ion Batteries
-
Lead-Acid Batteries
-
Flow Batteries
-
Sodium-Based Batteries
-
Others
-
On grid
-
Off grid
-
Customer-owned
-
Third-party Owned
-
Utility-owned
-
Below 100 MWh
-
Between 100 to 500 MWh
-
Above 500 MWh
-
Residential
-
Commercial & Industrial
-
Utility Scale
-
North
-
South
-
East
-
West
-
Battery Pack and Racks
-
Energy Management Software (EMS)
Geography Assessed
-
North India
-
South India
-
West India
-
East India
-
Competition
-
Mergers, Acquisitions, and Investments
-
Funding Timeline
-
Company Profiles
Companies Covered in the India BESS Market
-
Tata Power Renewable Energy Limited
-
Adani Energy Solutions Limited
-
JSW Energy Limited
-
Amara Raja Energy & Mobility Limited
The study covers a total of 12 India BESS Market companies. To know more, please reach out to [email protected]
What is driving growth in the India BESS market? +
Which application segment dominates the India BESS market? +
Which regions are leading BESS deployment in India? +
What are the key technology and pricing trends in the India BESS market? +
What is the future outlook of the India BESS market? +
Looking for a Section from Report? Start your Partial Purchase Request
Table of Contents
- 1.Research Methodology
- 1.1.Research Objective
- 1.2.India BESS Market Definitions
- 1.3.Research Design and Procedure
- 1.4.Data Collection Methods
- 1.5.Research Methodology
- 1.6.Analytical Framework
- 2.India BESS Market Analysis
- 2.1.India BESS Market Overview
- 2.2.India BESS Market Past, Present & Future Performance
- 2.3.India Installed BESS Capacity
- 3.India BESS Market Segmentation
- 3.1.India BESS Market Segmentation
- 3.1.1.India BESS Market Segmentation by Application
- 3.1.2.India BESS Market Segmentation by Connection Type
- 3.1.3.India BESS Market Segmentation by Battery Type
- 3.1.4.India BESS Market Segmentation by Energy Capacity
- 3.1.5.India BESS Market Segmentation by Ownership Model
- 3.1.6.India BESS Market Segmentation by Storage System
- 3.1.7.India BESS Market Segmentation by Component
- 3.1.8.India BESS Market Segmentation by Region
- 3.1.India BESS Market Segmentation
- 4.India BESS Market Regional Analysis
- 4.1.India Installed and Projected BESS Capacity by States
- 4.2.India Lithium-ion Battery Production Plants by States
- 4.3.India BESS Deployment and Battery Manufacturing Capacity
- 5.India BESS Market Pricing Analysis
- 5.1.India Standalone BESS System Costs
- 5.2.India Standalone Battery Storage Costs
- 5.3.India BESS Capital Cost by Key Components
- 5.4.India BESS Market Component Cost Structure
- 5.5.India BESS Market Battery Technology and Maintenance Cost
- 6.India BESS Market Tendering & Auction Landscape
- 6.1.India Utility-Scale BESS Tendering Landscape & Deployment Pipeline
- 6.2.India BESS Market Tendering & Auction Landscape
- 6.3.India Standalone BESS Auction Tariff Trends & State-wise Price Discovery
- 6.4.India BESS Tender Tariff Trends
- 6.5.India BESS Standalone Storage Tenders
- 6.6.India BESS Tender Growth & ESS Pipeline Expansion Overview
- 6.7.Dependency, Duty Reforms & Localization Initiatives
- 7.India BESS Market Policies & Projects
- 7.1.Policies Driving Battery Storage Adoption Across India
- 7.2.India Key Current and Upcoming BESS Projects
- 8.India BESS Market Regulatory Landscape and Initiatives
- 8.1.Government Incentives, VGF Expansion & ISTS Waiver Support
- 8.2.ACC PLI Manufacturing Push & Maharashtra Energy Storage Policy
- 8.3.Geopolitical Impact on India BESS Policies & Market Growth
- 8.4.India Grid Modernization & Renewable Integration Initiatives
- 9.India BESS Market Technology Landscape
- 9.1.Comparison of Battery Storage Technologies Across Key Parameters 10. India BESS Market Competitive Landscape
- 10.1.India BESS Market Key Players Comparative Analysis
- 10.2.India BESS Market Share Analysis by Company and Segment
- 10.3.India BESS Market Key Players Infrastructure Capacity
- 10.4.India Grid-scale BESS Capacity Awarded by Players
- 10.5.Product Category Portfolio of India BESS Market Companies
- 10.6.End-User Segments of Leading India BESS Market Companies
- 10.7.Comparative Analysis of Key Players - Technology Implemented 10.8. India BESS Companies - Gigafactory Expansion Comparative Analysis
- 11.India BESS Market Mergers /Acquisitions/ Investments/ Divestments
- 11.1.Mergers /Acquisitions/ Investments/ Divestments
- 12.India BESS Market Funding Timeline
- 12.1.Funding Timeline
- 13.India BESS Market Company Profiles
- 13.1.Player 1 - Business Overview
- 13.1.1.Product Portfolio
- 13.1.2.Business Highlights
- 13.1.3.Business Financials
- 13.2.Player 2 - Business Overview
- 13.2.1.Product Portfolio
- 13.2.2.Business Highlights
- 13.2.3.Business Financials
- 13.3.Player 3 - Business Overview
- 13.3.1.Product Portfolio
- 13.3.2.Business Highlights
- 13.3.3.Business Financials
- 13.4.Player 4 - Business Overview
- 13.4.1.Product Portfolio
- 13.4.2.Manufacturing Facilities and Capacity
- 13.4.3.Business Highlights
- 13.4.4.Business Financials
- 13.5.Player 5 - Business Overview
- 13.5.1.Product Portfolio
- 13.5.2.Business Highlights
- 13.5.3.Business Financials
- 13.6.Player 6 - Business Overview
- 13.6.1.Product Portfolio
- 13.6.2.Business Highlights
- 13.6.3.Business Financials
- 13.7.Player 7 - Business Overview
- 13.7.1.Product Portfolio
- 13.7.2.Business Highlights
- 13.7.3.Business Financials
- 13.8.Player 8 - Business Overview
- 13.8.1.Product Portfolio
- 13.8.2.Business Highlights
- 13.8.3.Business Financials
- 13.9.Player 9 - Business Overview
- 13.9.1.Product Portfolio
- 13.9.2.Utility-Scale Solar and Energy Storage Project
- 13.9.3.Business Highlights
- 13.9.4.Business Financials
- 13.10.Player 10 - Business Overview
- 13.10.1.Product Portfolio
- 13.10.2.Business Highlights
- 13.10.3.Business Financials
- 13.11.Player 11 - Business Overview
- 13.11.1.Product Portfolio
- 13.11.2.Business Highlights
- 13.11.3.Business Financials
- 13.12.Player 12 - Business Overview
- 13.12.1.Product Portfolio
- 13.12.2.Business Highlights
- 13.12.3.Business Financials
- 13.1.Player 1 - Business Overview
- 14.India BESS Market Challenges
- 14.1.India BESS Market Challenges Overview
- 14.1.1.India BESS Market Challenges
- 14.1.India BESS Market Challenges Overview
- 15.India BESS Market Opportunities
- 15.1.India BESS Market Opportunities Overview
- 15.1.1.India BESS Market Opportunities
- 15.1.India BESS Market Opportunities Overview
- 16.India BESS Market Future Outlook
- 16.1.India BESS Market Future Outlook
- 16.2.India BESS Market Scenario Analysis
- 16.3Evolving Demand for BESS in India
- 16.4.India Renewable Energy Demand & Targets 2030
- Limitations of the Study
Related Reports - Energy and Utilities